Thursday, October 6, 2016
Sunday, October 2, 2016
Wednesday, September 28, 2016
Saturday, September 24, 2016
Friday, September 9, 2016
Price vs Value
11:00:00 AM
Her friend saw it and said: "Wow! That's a very obvious place to show off your new phone."
The girl smiled and replied, "I'm playing the piano that is worth tens of thousands and all you can see is a phone that costs only a few thousand?"
The girl's mother said to the girl, "You are staying in a mansion that is worth a few million and all you can see is a piano that is worth a less than a hundred thousand?"
The girl's father walked in and said to her mother, "You are married to a billionaire and all you can see is a mansion that only costs a few million?"
Life Insurance has helped many families solved millions ringgit of debt and daily living expenses but all people talked about is the few thousands of premium.
Many merely focus on the price and not the value.
This is also why many remember how much insurance premium they serve but forgot how much coverage they are being protected.
"Price is what you pay. Value is what you get." - Warren Buffet
Saturday, September 3, 2016
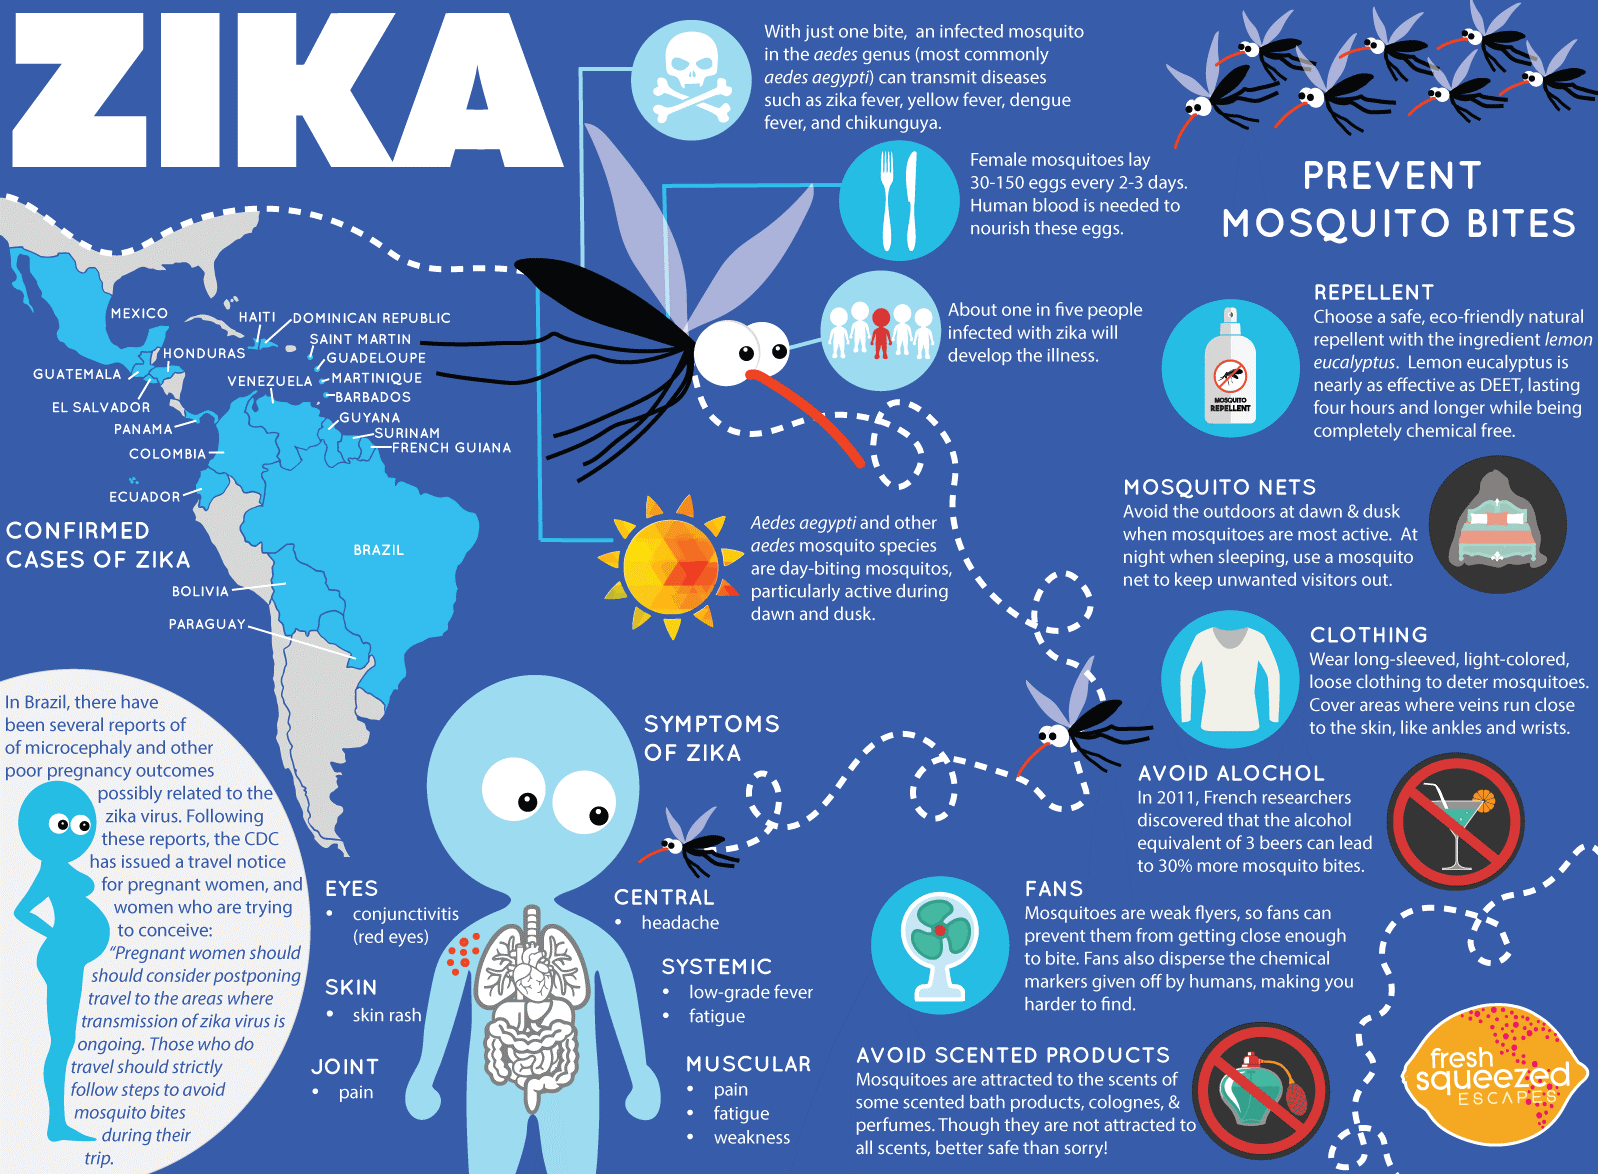
Zika : Do medical insurance / takaful policies covers?
11:43:00 AM
Many years back, Malaysia was surprised with Japanese Encephalitis (JE) spread by mosquitoes.
Same as Zika, illnesses or fever that is caused by Zika is still fairly new in Asia. Malaysia has only detected one case so far.
The Health Ministry is working round the clock to handle this issue.
So far, Zika is still in review for insurance and takaful policies because there isn't any cure or vaccine found.
Thus, such outbreak will be normally handled by the government.
It is compulsory that all Zika related cases are referred to Government Hospitals.
Wednesday, June 1, 2016
Does Your Cancer Coverage Cover You Full?
5:59:00 PM
No comments
As the title says, does your cancer coverage cover you full?
What does that mean?
Many of the Insurance Companies' Medical Benefits (a.k.a. Medical Card) cover in-patient and out-patient cancer treatment. We all know that if we are admitted, all treatment related expenses will be covered by Insurance Companies' Medical Benefits (subject to no exclusion).
What about Out-Patient Cancer Treatment?
Out-Patient Cancer Treatment Benefit simply means Cancer Treatment (Radiotherapy, Chemotherapy) that is done without admitting to the hospital. More often, doctor will need to do Examination, give Consultation and sometimes prescribe the patient with some take-home medicine.
When the question asked, whether your Cancer Coverage provides you with full cover, it means whether it covers Doctor's Examination, Consultation and Take-Home Medicine during an Out-Patient Cancer Treatment or not.
Check your policy for your Medical Benefits definition / write-ups and see if it covers you with Doctor's Examination, Consultation and Take-Home Medicine during an Out-Patient Cancer Treatment.
If it does not cover, then you might face a hefty charges from the hospital, if you are required to go through such treatment.
Contact Us to know how you can make your Cancer Coverage more comprehensive!
Saturday, July 11, 2015
Company Group Insurance, Are You Fully Protected?
11:33:00 PM
No comments
Majority of us are working adults, we work for companies as accountants, engineers and many more positions.
Most of the time when I go out to the field and approach people about getting a Personal Protection Programme, I always hear people answered, "My company covers me well" or "I got company insurance already" and many other variants with similar meaning.
When I probe further, many of these working adults have NO IDEA what coverage the company has prepared for them. Most of them thought that they are 100% covered but sadly, that is not the case for 99% of the working people.
When they finally found out that their company insurance are SO LOW, to the extend of only RM10,000 Annual Limit, they were panic and asked my advice on helping them to set up a Personal Protection Programme.
Just to clear the cloud, let me show you possible 3 scenarios about Depending on Company Group Insurance.
Mind you, the above scenario is the MOST IDEAL one, don’t you agree?
Now what if you change job due to better offer?
After 12 months, are you safe? Maybe yes if the coverage is the same or more than your previous entitlement in your old company.
------------------------------------------------------------------------------------------------------------
Seriously, unless you are the owner of the company or the CEO for the very least, why would you want to depend on a TEMPORARY SOLUTION to solve your PERMANENT PROBLEM?
Contact Me for more information on how you can set up your Personal Protection Programme today!
Most of the time when I go out to the field and approach people about getting a Personal Protection Programme, I always hear people answered, "My company covers me well" or "I got company insurance already" and many other variants with similar meaning.
When I probe further, many of these working adults have NO IDEA what coverage the company has prepared for them. Most of them thought that they are 100% covered but sadly, that is not the case for 99% of the working people.
When they finally found out that their company insurance are SO LOW, to the extend of only RM10,000 Annual Limit, they were panic and asked my advice on helping them to set up a Personal Protection Programme.
Just to clear the cloud, let me show you possible 3 scenarios about Depending on Company Group Insurance.
Ideally, the above scenario (Scenario A) is what everyone wants.
When are 100% healthy for entire life, or, if there is any claims during our employment, company or company group insurance will bear ALL the Medical Fees.
When we retired, we are also 100% healthy till we die, or, we are already multi millionaire that we can bear ALL the Medical Fees if we fall sick, before we die.
Mind you, the above scenario is the MOST IDEAL one, don’t you agree?
Scenario B depicts a very realistic but yet not-so-serious scenario whereby there is a claim somewhere in between and one had to either:
- Become a multi millionaire after retire so one can bear ALL the medical fees in the future after retire
- Chose to work for another 15 years (Company Group insurance covers maximum up to age 70) because wanted to depend on Company Group Insurance.
If one has a Personal Medical Insurance (covers till age 91) + Income Replacement (covers till age 100) when one started working, will the above scenario changed, slightly?
Now what if you change job due to better offer?
You can’t be working in the same company until you retire, unless you know you can retire as the CEO of the company, right?
When you change jobs, your existing coverage from your previous company group insurance will also expire, leaving you with no coverage at all. The coverage from your new job will most probably commence after your probation (if not, immediately) and ALL Pre-Existing Illnesses will NOT be covered for at least 1st 12 months.
What are you going to do if the same illness happens again?
The answer is very simple, you bear ALL the Medical Fee for that treatment!
After 12 months, are you safe? Maybe yes if the coverage is the same or more than your previous entitlement in your old company.
What if the new company offers LESSER coverage?
------------------------------------------------------------------------------------------------------------
Seriously, unless you are the owner of the company or the CEO for the very least, why would you want to depend on a TEMPORARY SOLUTION to solve your PERMANENT PROBLEM?
Contact Me for more information on how you can set up your Personal Protection Programme today!
Wednesday, February 11, 2015
What Will They Say? What Will You Say?
4:31:00 PM
No comments
When Hospital, Bank and Insurance Company said these, what will you do?
Hospital : Financial Difficulty
1. Your illness is very serious!
2. But it is curable!
3. However, it will cost a lot!
Bank : Makes This Works
1. We pity you!
2. But we have rules to follow!
3. If you delay your mortgage repayment, we have to take away your house!
Insurance : Safeguard Your Money
1. We allow you to claim for your illness!
2. Once confirm diagnosis, we will pay RM500,000 lump sum cash
3. Your future premium will be contributed by company
What will you do?
Many people around us...
When they fall sick, they want to buy Medical Insurance.
When they are old, wants to buy Life Insurance.
When they met with accident, wants to buy Personal Accident Coverage
... but too bad, too late already!
Monday, August 4, 2014
The Basics of Travel Insurance
7:12:00 PM
No comments
Awareness of Travel Insurance has increased tremendously following the incident of MH370 and MH17. Many are worried that they might be injured or even dead when flight catastrophes happen. The main thing people are worried about is how their family members can continue on with their demise or lost of earning ability.
Travel insurance can help cover medical expenses or financial losses you might incur while traveling. It's often pitched as the best protection for those traveling domestically or overseas. This article will explain what kind of coverage you need before you sign on the dotted line and start paying for protection against the unforeseen and unpredictable.
What Does Travel Insurance Cover?
There are four main categories of travel insurance:
- Trip cancellation
- Medical Expenses and Other Expenses
- Emergency medical evacuation
- Accidental death/flight accident
Trip Cancellation Insurance
As its name implies, trip cancellation insurance (sometimes known as trip interruption insurance or trip delay insurance) covers you in the event that you or your traveling companions need to cancel, interrupt or delay your trip.
Policies differ in terms of which reasons are acceptable, but it's fairly typical for this insurance to cover cancellation or interruption for the following reasons:
- Sudden business conflicts
- Delay in processing your visa or passport
- Illness or injury
- Weather-related issues
Some policies may include additional coverage, which would insure you against one or more of the following events:
- An act of terrorism
- The vendor (cruise line, tour company, airline) going out of business
- An accident on the way to the airport
- Jury duty
The insurance pays the difference between the refund you get from the vendor and the amount you originally paid for the trip.
Medical Expenses and Other Expenses
Reimburses the actual necessary and reasonable medical, surgical or hospital charges and emergency dental treatment charges incurred as a result of accidental bodily injuries or death, illness during the Journey including repatriation costs, outside the Insured Person‘s home country for Overseas/Annual Coverage.
Domestic Coverage shall be limited to reasonable medical, surgical or hospital and emergency dental treatment incurred as a result of accidental bodily injuries or death during the Journey including transportation cost incurred in moving the Insured Person within Malaysia. Other benefits include follow up treatment, funeral expenses, compassionate care and child care benefit.
Emergency Medical Evacuation Insurance
This type of insurance provides coverage for medically necessary evacuation and transportation to medical facilities. These costs can easily reach USD10,000 out of pocket if you don't have coverage. This becomes extremely useful should you become stranded in a remote rural area without easy access to needed facilities.
Accidental Death and Flight Accident Insurance
These types of insurance pay benefits to a traveler's surviving beneficiaries, as with life insurance. Benefits are paid out in the event of an accident resulting in death or serious injury to the traveler.
There are other more benefits which are too long to be listed here
Why Travel Insurance exist? Simple.
It is because of protection, Income and Medical Protection.
Contact Us for more information about Allianz Travel Care, which covers risk such as Act of Terrorism
Subscribe to:
Posts (Atom)