Life Insurance Business

"Malaysia’s life insurance business is expected to grow by 9% to 10% in 2013" - LIAM

Critical Illness Coverage

Do you need critical illness cover (also known as 36 dread diseases cover)?

Increasing Medical Cost

Healthcare costs in Malaysia increases about 10% every year - approximately double the inflation rate.

2 out of 3 people will be diagnosed with Critical Illness

If you think that the premium is high, what about the cash needed for a critical illness?

Get to know us today!

“In the next 5 years, without changing our current situation, can we achieve the time, money and lifestyle that we want?”

Monday, June 17, 2013

Revolutionary Way to Run Life Insurance Business


Few industries outside of the financial services industry offer the potential for relatively inexperienced professionals to make significant income within their first year of employment. Within the financial services industry itself, few careers match the opportunity for as quick and large a paycheck as does being a life insurance agent. In fact, a hard-working insurance agent can easily earn more than $100,000 in his or her first year of sales.

But, success as an insurance agent doesn't come without a cost. Insurance agents hear "no" far more than they hear "yes". It's not uncommon for the "no" to come mixed with a fair amount of obscenities and the proverbial door in the face.

With the Revolutionary Way of running Life Insurance as a Business, Buss Consulting (M) Sdn Bhd has designed and restructure the reward structure to allow hardworking Life Insurance Businessperson to earn more as they progress - with the guidance of a Proven Success System.

Wednesday, May 15, 2013

Why Have Liability Insurance for a Business?


Insurance is an important part of any company's business plan. Insurance can save your company if you experience a catastrophic loss and protect your cash-flow when an unexpected accident occurs. Commercial general liability (CGL) insurance is an extremely important part of your business insurance, stepping in to help when an incident causes your company to be sued.


What Is CGL?

Simply put, CGL responds when your company is sued by another party. The suit can be the result of property damage caused by one of your employees or a claim for bodily injury to an employee or third party. CGL can also respond if you are sued for libel or slander as well as any harm your company causes to a property you rent. CGL provides protection by paying the legal fees associated with defending your company against the suit, as well as any settlement or court award. Most CGL policies offer protection against four different types of claims.

Bodily Injury And Property Damage Liability
Bodily injury and property damage liability is the cornerstone of CGL insurance. This coverage responds when an employee causes damage to a third party's property, such as when a plumber accidentally causes water damage to a customer's home. It also responds when a third party is injured by your company or its employees. A common bodily injury claim occurs when a customer slips on the floor of a retail store and injures himself, or when a construction worker accidentally drops a tool onto a passer-by.

Personal Injury Liability
Not to be confused with bodily injury, which physically harms an individual, personal injury liability focuses on words. Personal injury coverage responds when you, your employees or your company is sued for libel or slander. Typically, suits are launched with an accusation your company damaged a person’s or company's character, reputation or position in the community, due to libelous (written) or slanderous (spoken) defamatory statements. For your liability policy to respond, you cannot know the statements were untrue when they were stated.

Medical Payments
Occasionally, the best defense against being sued is acting proactively when an accident does take place. If someone is injured on your property or because of the acts of an employee, medical payments coverage will voluntarily pay for their medical bills without them requiring them to file a lawsuit. In many cases, rising to the occasion by offering to pay an injured person's expenses prevents a lawsuit and maintains the company's reputation within the community.

Tenant's Legal Liability
If you rent your office, retail outlet, warehouse or shop from another party, tenant's legal liability responds when you are held legally liable for causing damage to the property. If if you or your employees were to cause a fire that damages the property, tenant's legal liability coverage would respond to provide restitution to your landlord. Similarly, if a pipe were to burst and cause water damage, your CGL policy will step in to help.

What's Not Included
As broad as many CGL policies are, a number of standard perils are not covered by most policies. These include any claims involving environmental damage or pollution caused by your company or your employees. It excludes product liability claims when your products cause harm as well as claims due to your company's errors or omissions, also referred to as professional liability claims. Insurance products are designed to respond to all of these exclusions as well as almost any foreseeable peril, but these must be purchased separately from your CGL policy.


Sunday, April 7, 2013

Rich People Don’t Need Life Insurance?!


Really? Who says rich people don’t need life insurance? Would it surprise you to know that wealthy people are some of the biggest buyers of life insurance in the world. Would it shock you to know that they even borrow money to buy huge amounts of life insurance for tax reasons? Maybe they know something that the average person does not.

For most people life insurance buys peace of mind for their family’s future… to help pay funeral costs, or make sure a spouse can pay off the mortgage and fund their children’s college education. Simple but critically important needs so that the family does not go into financial ruin. The other good news is that the death benefit from that life insurance policy is generally tax-free to your beneficiaries.

But for people who make the big bucks— who can afford to pay for all those fancy financial advisors— the stakes are much higher. The wealthy figure that if they were smart enough to make it, they should be smart enough to keep it. Call it rich man’s wisdom: How to be rich and how to stay rich.

The wealthy usually own whole life insurance policies, also called cash value life insurance. These policies accumulate a cash value, and as long as you do not withdraw that cash, this value can grow tax-free until you withdraw it. If you wait until retirement to receive it you will likely be in a lower tax bracket so you will keep more of your investment.

One thing you can be sure of is that the wealthy HATE to pay tax. Especially after they’ve accumulated wealth and paid tax their entire life, it really irks them to know that if they die and leave it to their children their kids will pay big taxes to get it… in their minds it’s like letting the government double-dip!

This is not my viewpoint… it’s just the way it is. There’s been a lot of controversy over the estate tax issue in recent years, the same type of controversy you see between political parties. You can’t control whether or not to pay tax but you can literally buy those tax ringgit, often for sen on the ringgit, through the use of life insurance.

So, granted none of the heirs of wealthy people are likely to be in the poor house, but they sure don’t want to bequeath that money to the government if they can avoid it. That is why they have learned how to use life insurance for a fraction of their own hard-earned dollars.

You might not have millions of dollars in the bank but you should learn about the power and value of life insurance for your own financial picture. Take a couple of minutes to save some money by getting a FREE  life insurance quote now…it is more affordable than you think.

Your financial statement might be more modest but your desire to protect your family’s future is the same as that of a rich man’s. What do you think? We’d love to hear your thoughts on death (regarding life insurance of course) and taxes. Your turn to jump on the soap box!

Thursday, February 28, 2013

Malaysians Living Longer and Enjoying It More


For many years, Malaysia has focused on 2020, when the nation hopes to reach fully developed nation status. Then, not only will Malaysia be a different country (in terms of opportunity and per capita income), we will be living longer to enjoy it -- truly the best of both possible worlds.

Life expectancy for Malaysian women is expected to jump to 79 years in 2020, up from 77 years today, while Malaysian men could expect to live until 74.2 years, up from 71.9 today.

Life expectancy is largely a reflection of the overall quality of life in a nation. In the 1960s, average Malaysian life expectancy was around 54 years. But advances in medicine, better nutrition and more expendable income have contributed to a longer lifespan.

Our longevity numbers place us near the top third of all nations in life span, and suggest that we're on our way to becoming an aging nation.

What happens if we live too long? 

As we live longer and healthier lives, we risk outliving out assets. We could end up in poverty, relying on the government or family to cover our basic living expenses. Or we could become ill and incur unexpected medical costs that quickly deplete a lifetime of savings.

  1. How will your assets hold up if you need to dip into them for a critical illness or long term care?
  2. What options are available to you for emergencies?


Sunday, February 10, 2013

Why Buy Insurance For Parents?


There comes a time in every parent-child relationship where the roles reverse, where the parent becomes the child and the child becomes the parent. And when that change takes place, part of your responsibility is to make sure that your parents have a sound plan in place for the inevitable day when they are gone.

Buying life insurance for parents is not an easy thing to do, but it's important and necessary for so many people. Some children buy life insurance on their parents in order to make sure that there is enough money to pay for burial or final expenses when their parents die. Others buy life insurance on their parents in order to create or preserve an estate that can be passed along to surviving children.

Getting your parents Medical Insurance also help you, as children, in avoiding financial difficulties. Imagine your parents need RM100,000 for medical bill and you have another 2 siblings. If all siblings are working and have the ability to earn, each would have to fork out RM33,333.

What happens if your spouse disagree?

What happens if not all siblings are working and earning money?

Regardless of your reasons for needing to buy life insurance for your parents, one thing that most insurance companies will look require before issuing a policy is called "insurable interest." In the most basic sense, insurable interest is proof that, should your parents die, you would suffer some kind of financial loss. This requirement protects insurance companies from issuing policies that are taken out by children who simply think that their parents may not have long to live and create a fortune by purchasing big life insurance on them.

Once it has been established that you do in fact have an insurable interest, you need to choose the type and amount of insurance coverage to purchase.

Another consideration should be your parents' current health status. It can be difficult, even at a younger age, to purchase life insurance if you have serious medical conditions.


Sunday, February 3, 2013

Why Children Need Health Insurance?

Did you know . . .

That children without insurance are less likely to get care for such things as ear infections which can lead to lifelong consequences like loss of hearing?

That children with insurance are more likely to be healthy and that healthy kids do better in school?

That children with insurance miss fewer days from school and because of this their parents also miss less time from work?

That healthy children still need check-ups, shots and regular dental care so they can stay healthy?


Most importantly, when you decide to get your children Life / Health Insurance, you directly guarantee his or her future insurability.

If he or she diagnosed with diseases during young, he or she may not be insured in the future anymore. Thus, getting him or her insured at young age will directly guarantee his or her future.


Monday, December 17, 2012

Top 5 Life Insurance Myths


Life insurance is not a simple product. Even term life policies have many elements that must be considered carefully in order to arrive at the proper type and amount of coverage. But the technical aspects of life insurance are far less difficult for most people to deal with than trying to get a handle on how much coverage they need and why. This article will briefly examine the top 5 misconceptions surrounding life insurance and the realities that they distort. 


Myth #1: I'm Single and Don't Have Dependents, so I Don't Need Coverage
Even single persons need at least enough life insurance to cover the costs of personal debts, medical and funeral bills. If you are uninsured, you may leave a legacy of unpaid expenses for your family or executor to deal with. Plus, this can be a good way for low-income singles to leave a legacy to a favorite charity or other cause. 

Myth #2: My Life Insurance Coverage Needs Only Be Twice My Annual Salary

The amount of life insurance each person needs depends on each person's specific situation. There are many factors to consider. In addition to medical and funeral bills, you may need to pay off debts such as your mortgage and provide for your family for several years. A cash flow analysis is usually necessary in order to determine the true amount of insurance that must be purchased - the days of computing life coverage based only on one's income-earning ability are long gone. 

Myth #3: My Term Life Insurance Coverage at Work Is Sufficient 
Maybe, maybe not. For a single person of modest means, employer-paid or provided term coverage may actually be enough. But if you have a spouse or other dependents, or know that you will need coverage upon your death to pay estate taxes, then additional coverage may be necessary if the term policy does not meet the needs of the policyholder. 

Myth #4: Only Breadwinners Need Life Insurance Coverage
Nonsense. The cost of replacing the services formerly provided by a deceased homemaker can be higher than you think, and insuring against the loss of a homemaker may make more sense than one might think, especially when it comes to cleaning and daycare costs. 

Myth #5: I'm Better off Investing My Money Than Buying Life Insurance of Any Kind
Hogwash. Until you reach the breakeven point of asset accumulation, you need life coverage of some sort. Once you amass RM1 million of liquid assets, you can consider whether to discontinue (or at least reduce) your million-dollar policy. But you take a big chance when you depend solely on your investments in the early years of your life, especially if you have dependents. If you die without coverage for them, there may be no other means of provision after the depletion of your current assets. 

The Bottom Line
These are just some of the more prevalent misunderstandings concerning life insurance that the public faces today. Therefore, there are many life insurance questions you should ask yourself. The key concept to understand is that you shouldn't leave life insurance out of your budget unless you have enough assets to cover expenses after you're gone. 


Monday, December 10, 2012

Why Single Women Need Life Insurance?

If you are a single woman, chances are you haven’t given much thought to purchasing a life insurance policy. But as the head of your household, even if your household consists of just you, there are some compelling reasons why you should consider purchasing a life insurance policy.


Single Woman with No Children:

Have you ever thought about what would happen to your estate if you were to die unexpectedly? Who will be responsible for your debts (car loans, education loans, mortgage, estate taxes, etc.) if your estate does not cover these costs?

Well, chances are your family will be responsible. Can you imagine your aging parents or other loved ones who are living on a fixed income having to pay off your car, school loans and mortgage because there wasn’t enough money in your estate to cover these costs? And with the housing market still sluggish, selling a home may not be an immediate option to pay off these debts. But a life insurance policy can cover these costs and provide your loved ones with peace of mind during this difficult period. And, if you choose to remain single, your life insurance can accumulate cash value to help provide a secure retirement for yourself.

As a young, healthy, single woman, you have the opportunity to purchase a life insurance policy at reduced premiums. However, the older you are, the higher your premiums will be. Locking in a low rate for a fixed period of time is an excellent way to secure an affordable life insurance policy. One other benefit, the cash value of your insurance policy can also be used to secure loans.

Keep in mind, that should you decide to get married and/or have children, your life insurance needs will increase. Re-evaluating your policy with each life change is a smart move.

Divorced and Widowed Single Moms:

Did you know that only 4 percent of all life insurance policies sold in 1997 were purchased by divorced or widowed women (“The Women’s Market: Myth & Reality,” LIMRA International, 1999)? This startling fact means that a majority of the 11 million single moms in the U.S. today are without life insurance. 

As a single mom, if you do not have life insurance, you run the risk of not having your children’s basic needs met should you die unexpectedly, especially if there is not a father in the picture. (Note: In addition to providing for your children’s college tuition and living expenses, single moms may need to factor in additional expenses such as child care and domestic help that a life insurance policy could cover).

The Amount of  Life Insurance You Need is Determined By:

  • Your age
  • Debt
  • Whether or not you have children
  • The number of children you have
  • The ages of your children
  • Your overall health
  • The amount of money your family will need to survive
What Type of Life Insurance (term, whole life, annuity, etc) Should You Purchase?
Ask us for policy options, terms and conditions, premiums and the ability to change your policy should you have a major life change such as getting married and/or having children. But before you do, spend some time educating yourself on the types of policies available and become familiar with the terminology.
Adapted from : http://singlemindedwomen.com/money-tips/why-single-women-need-life-insurance/

Saturday, December 8, 2012

Who Actually Need Insurance?

Majority of the society think that they belong to a group of people that does not need insurance.

The rich will always think that only the average or poor need insurance as they are not afford to pay for medical bills and etc.

The average / poor always has the perception that only the rich need insurance as they can afford to buy it.

Actually, doesn't matter if we are rich or average or poor, we all need insurance because insurance plays its respective role to the rich and the average or poor.


The Rich

If you are rich, I am pretty sure that you have a lot of property and money. You may also have a very high income and be able to afford many things for yourself and your family.

But, did you realize? If you were diagnosed with critical illness last night, your family will need to sell your property(ies), and use up all your savings just to pay your medical bills?

Not only your property will be sold in a cheaper price due to urgency, the time taken for the deal to be sealed can be frustrating! Thus, it may not be enough for your medical bills and will cause your family to go poor and end up borrowing money from others.

With insurance, you do not need to use up your savings or sell your property to pay for your medical bills. Living expenses for you and your family during the time when you are not able to work can also be provided by insurance.

In another words, your family will not suffer, lose their property and income.

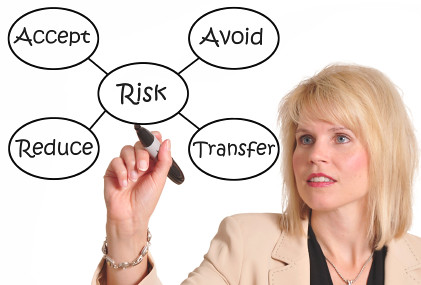
All you need to do is to "transfer" small part of your income to insurance so you can protect the rest of them.

The Average / The Poor

For the average / the poor, not only your income is just enough for your daily expenses, you might have other commitments too.

And did you realize? If your income is just enough to cover your daily expenses, what will happen if you are diagnosed with critical illness yesterday and you lose the ability to earn money anymore? What will happen to your family and your children (if you are married with kids)?

Well, you can send your children to orphanage but the fact is, many orphanages in Malaysia also need funding from the generous!

Won't you feel guilty to let your children, that you loved so much, live in a tough environment and perhaps being marginalized by others due to lack of money?

Very obvious, with insurance, you are able to "create" your life saving fund and perhaps some inheritance immediately, although your income is not high.

It doesn't matter if you are diagnosed with critical illness, paralyzed or passed away,  your responsibility to take care of your family can be accomplished.

Try to adjust your budgeting a little bit so you can at least get minimal insurance coverage to protect yourself.

Even though the coverage is small, the benefit from insurance will mean a lot to your family because it proves that your love stays on even though you are not around. Your love for your family will always be in their heart.
Thursday, December 6, 2012

Private Hospitals in Malaysia


According to Association of Private Hospitals of Malaysia (APHM), there are 106 private hospitals in Malaysia that has registered as their member. I am sure there are a few that are not registered as their member.

Source : Association of Private Hospitals of Malaysia

Number of Private Hospitals that are registered with Allianz Life Insurance Malaysia Berhad as Panel Hospitals is 106 too.